Business finance for essential services
Finance for the businesses that care for Australia
Fit-outs, equipment, buying a practice and cash flow around NDIS, Medicare, CCS and aged care payment cycles, for the clinics, centres and providers Australians rely on.
- No credit check to enquire
- No spray-and-pray
- $20k – $5m secured
Quick fit-out check
No credit check to enquire
Asking what's possible leaves your credit file untouched. A credit check only comes up once you choose to proceed.
No spray-and-pray
Your enquiry isn't auctioned off to a list of lenders. One team reads it and matches it with care.
A real person on your file
A specialist who understands practices and care providers calls you. Accurate form answers mean the right option on the first call.
Who we fund
Built around how your sector gets paid
A dental practice, a childcare centre and an NDIS provider all look different to a lender. Start with yours.
Payment cycles
You pay your team every fortnight. Your funding doesn't always keep pace.
Most care businesses deliver first and get paid later. Growth makes the gap wider. Here's how each system's timing works, from official guidance, and how to bridge it without stress.
- NDISRecorded 'my provider' claims usually paid in 2–3 business days; others about 10
- Support at HomeClaimed after each service is delivered; validated before payment
- Child Care SubsidySession reports due within 14 days after the week of care
- Bulk billing incentiveExtra 12.5% on eligible MBS benefits, paid quarterly
- PBSPaid weekly for pharmacies claiming online
What we fund
From the first consulting room to the second site
Fit-outs, equipment, buying or buying into a practice, premises, a second site or clearing a tax debt — how each is usually funded.
Signature tool
Cost the whole project, not just the builder's quote
Build, fees, equipment, furniture, IT and the months before the rooms are full. Our free calculator adds it all up, shows what property equity could cover, flags what might suit unsecured finance, and warns you if your buffer runs out before income catches up.
- Equipment lines tailored to GP, dental, allied, vet, pharmacy, childcare and care providers
- Secured vs unsecured split, with no interest rates assumed
- Month-by-month runway and a document checklist for your sector
How it works
Four steps, one team, no runaround
- 1
Tell us the plan
About 60 seconds: what you're funding, roughly how much, your state and whether there's property. No credit check.
- 2
A real person calls
A specialist who understands practices and care providers reads your enquiry and rings to fill in the picture.
- 3
Options that fit
Secured, unsecured or both, sized to your project and your payment cycles. You decide whether to go ahead.
- 4
Documents, approval, funding
Only once you proceed. We tell you exactly what's needed, and funds go to you or straight to the builder or supplier.
Second opinion
Common beliefs, checked
BeliefLenders won't touch a business paid by the government in arrears.
In practiceRegular NDIS, CCS, Medicare and PBS income is exactly what lenders like to see in bank statements. The timing just needs the right facility.
BeliefYou need two years of profit to fund a fit-out.
In practiceTrading history helps, but a new practice can often borrow with property security, a lease, quotes and a sensible ramp-up plan.
BeliefAsking about finance will hurt my credit file.
In practiceNot here. There's no credit check when you first enquire; it's only discussed once you choose to proceed.
BeliefTax debt means the answer is automatically no.
In practiceATO and payroll tax debt are considered case by case. Being upfront gets you a real answer faster.
Guides
Plain-English guides for practice owners
Researched from official 2024–2026 sources and written for Australian clinics, centres and care providers.
Payroll Tax for Medical Centres: NSW and Victoria in 2026
Why contractor GP arrangements drew payroll tax assessments, how NSW and Victoria responded, and what practice owners should review in 2026.
Instant Asset Write-Off for Clinics: $20k, Now Permanent
How the now-permanent $20,000 threshold works per asset, what it doesn't do for cash flow, and how practices plan equipment purchases around it.
Clinic Fit-Out Timeline: From Lease to First Patient
The stages of a clinic fit-out, when cash is needed at each one, and the delays that catch owners out.
What It Costs to Start an NDIS Business in Australia
A practical list of NDIS start-up costs, the working capital gap most new providers underestimate, and how to fund both.
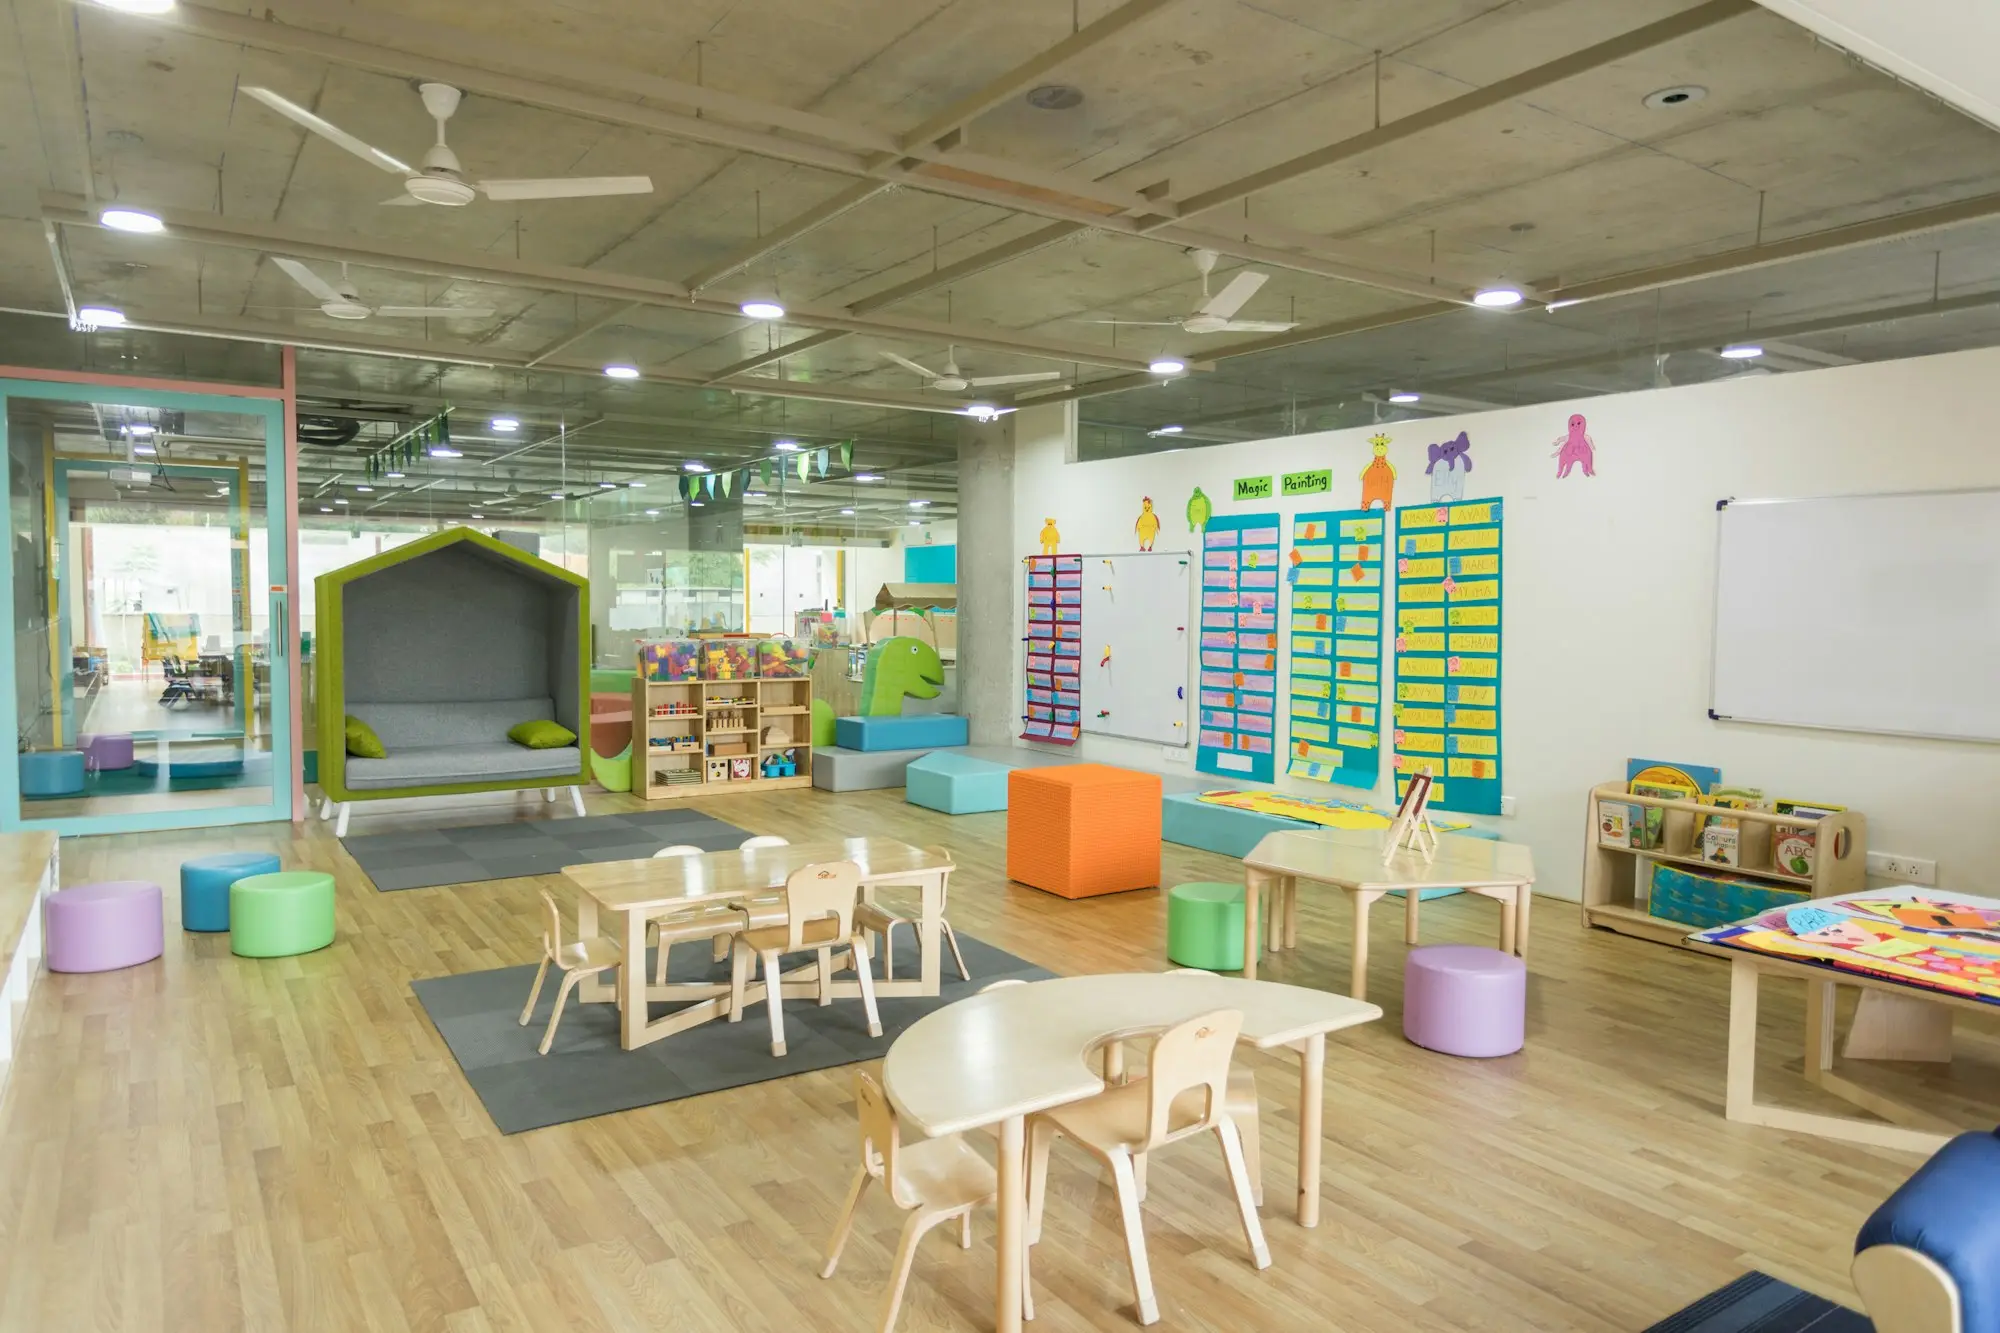
New Childcare Centre Ramp-Up: Funding the Empty Rooms
Why new centres burn cash while rooms fill, how to forecast occupancy honestly and how to size the buffer.
Buying a Practice: Due Diligence Checklist for Health
What to check before you buy a clinic, pharmacy or centre, organised the way lenders and advisers think about risk.
Questions practice owners ask us
What kinds of businesses does Essential Finance help?
Essential-services businesses: GP clinics and medical centres, dental practices, allied health clinics, specialists, childcare and early learning centres, aged care and home care providers, NDIS providers, community pharmacies and vet clinics. We arrange business finance only, not personal or patient loans.
How much can a practice or care provider borrow?
Property-secured business loans run from $20,000 to $5,000,000 as first mortgages, second mortgages or caveats over residential or commercial property. Unsecured, cash-flow and line-of-credit options for trading businesses typically run from $5,000 to $500,000, sized on turnover and bank statements.
Does enquiring affect my credit score?
No. There's no credit check when you first enquire. A credit check is only discussed once you've seen your options and decided to go ahead.
Will my details be sent to lots of lenders?
No. We don't spray your enquiry across a list of lenders. One team reads it, a real person calls you, and we match your situation properly.
Can you help with cash flow while we wait on NDIS, CCS or Medicare payments?
Yes. A line of credit or short-term facility can bridge the time between paying your team and being paid. Our claims gap calculator estimates how much cash is tied up, and our payment cycles pages explain each system's timing.
Do you publish interest rates?
No. Every facility is priced on the business's own circumstances: the security, trading history, amount and term. A specialist will talk you through real options once they understand your situation.
Can you help if we have ATO or payroll tax debt?
Often. ATO debt and past credit issues are considered case by case. Some practices use property-secured loans to clear or consolidate tax debt into a repayment they can manage.
Can a brand-new practice or centre get finance?
Yes, usually with property security, because there's no trading history yet. A lease, quotes and a realistic ramp-up forecast make the application credible. Our fit-out and equipment calculator helps you size the whole project, including the buffer.
More answers on our FAQ page, or see how it works.
Let's look after the business side
Tell us what your practice, centre or service needs in about 60 seconds. No credit check to enquire, no lead farming, and a real person calls you back.
No credit check to enquire
No spray-and-pray
A real person on your file