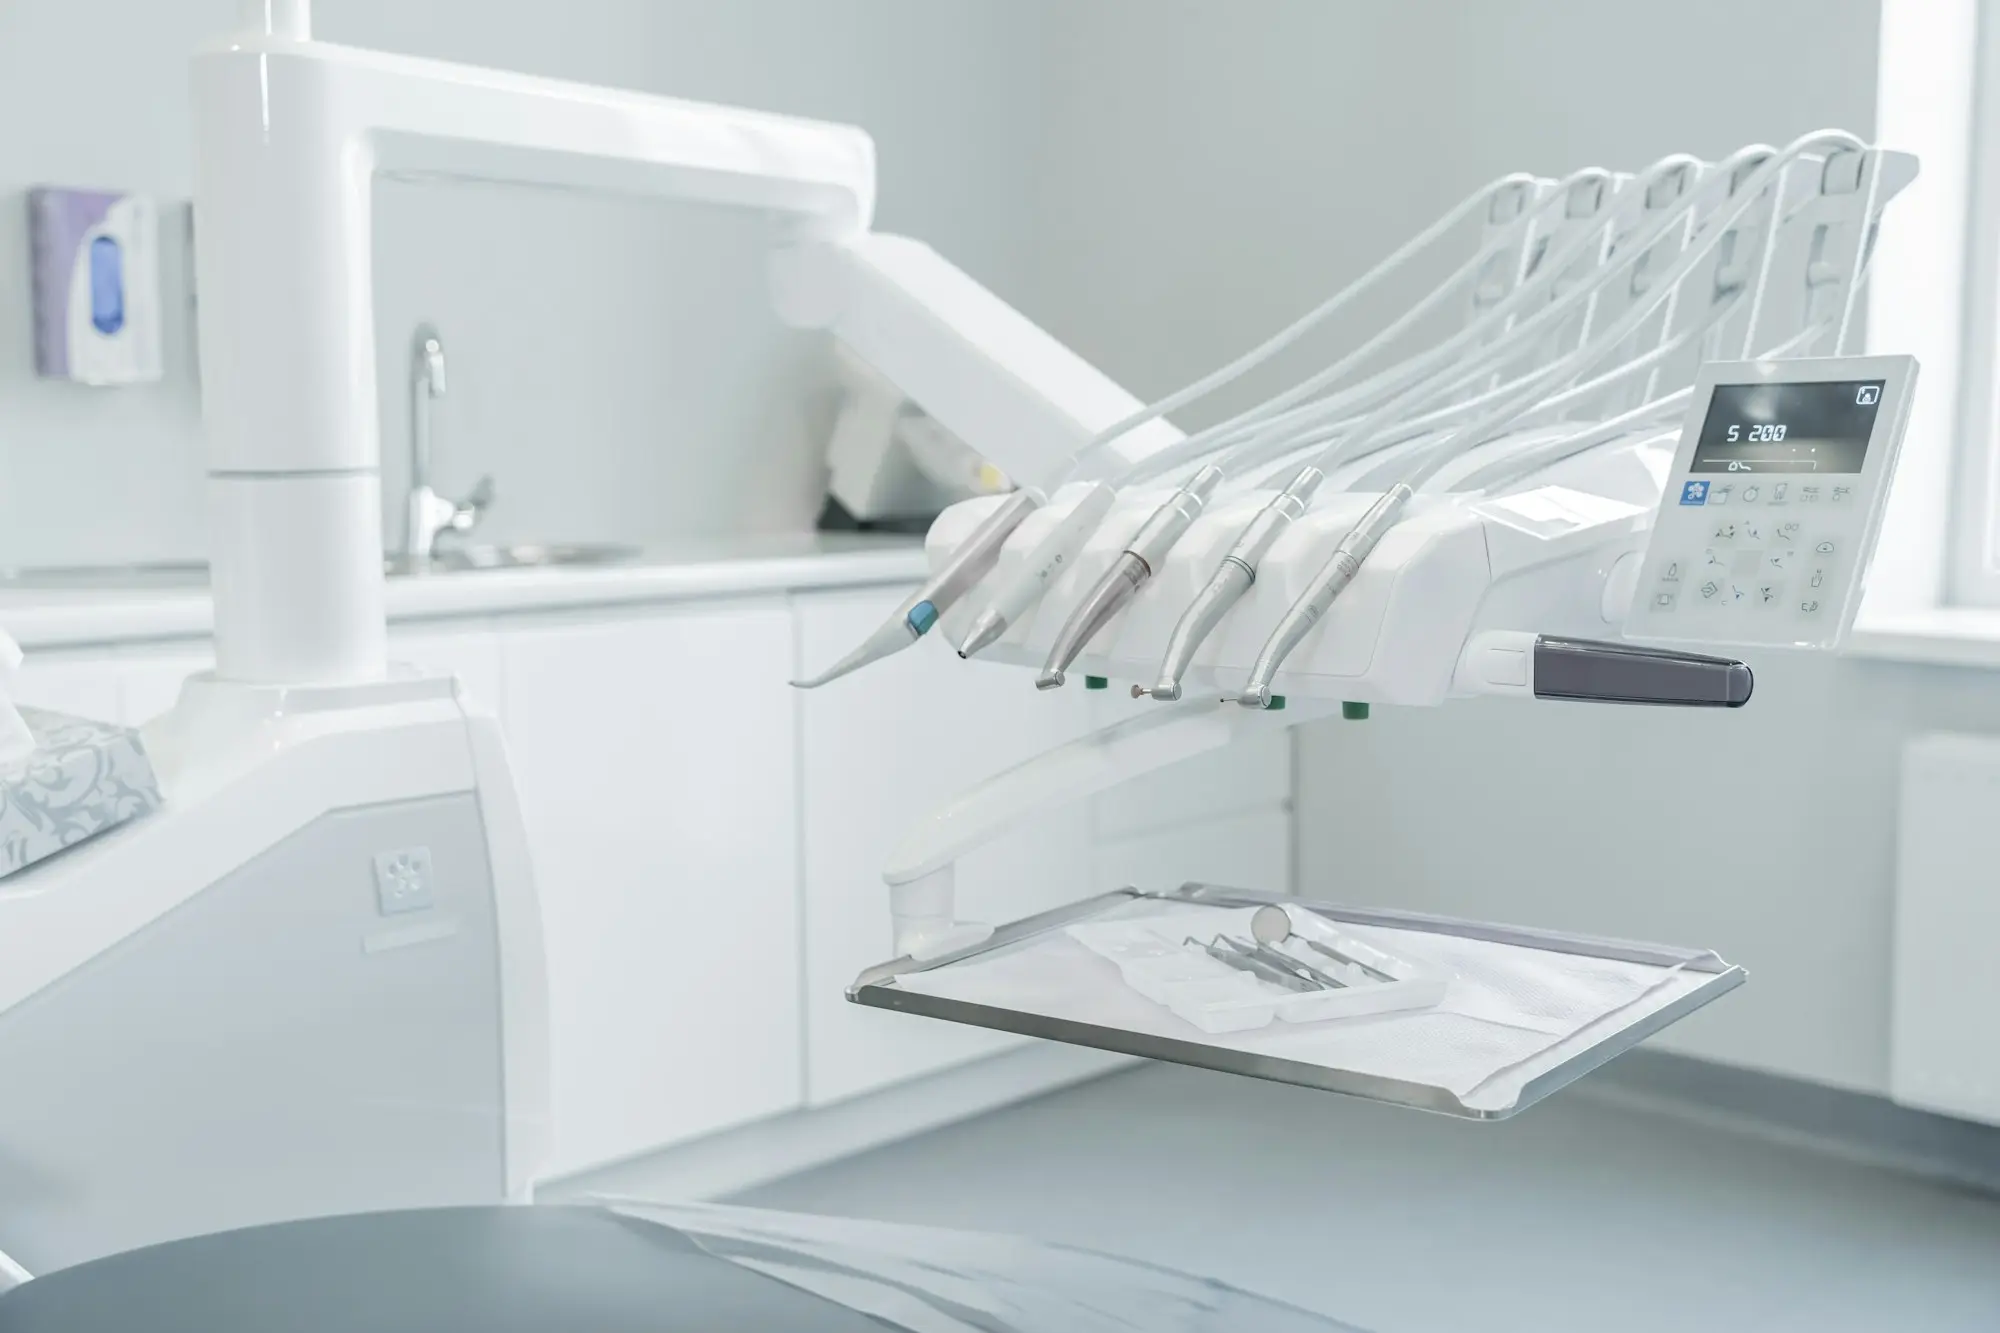
Quick answer
Dental equipment finance funds chairs and delivery units, intraoral and extraoral imaging including OPG and CBCT, intraoral scanners, milling units, sterilisation equipment and practice IT. Trading practices can often use unsecured facilities typically between $5,000 and $500,000, sized on turnover and bank statements. Larger packages, or a new surgery, are commonly funded with property-secured loans from $20,000 to $5,000,000. Repayments should match the equipment's working life.
Key points
- Covers chairs, imaging (including CBCT), scanners, milling, sterilisation and IT
- Digital dentistry equipment can create new revenue, which strengthens the case for finance
- Installation, room works and training belong in the funded amount
- Items under $20,000 each may qualify for the instant asset write-off for eligible small businesses
- Loan size
- $5k – $500k unsecured; up to $5m secured
- Common items
- Chairs, CBCT, scanners, milling
- Include
- Installation, room works, training
- First step
- 60-second enquiry, no credit check
Dental equipment has changed more in the past decade than in the thirty years before it. Film has given way to digital sensors, impressions to intraoral scans, lab-made crowns to chairside milling, and panoramic imaging to CBCT in many practices. Each step brings better care and new revenue, and each comes with a significant price. Dental equipment finance lets a practice adopt new technology on a timetable that suits its cash flow.
What dental equipment is commonly financed?
| Equipment | Notes |
|---|---|
| Chairs and delivery units | Often replaced one surgery at a time; include installation and plumbing connections |
| Intraoral X-ray and sensors | A basic but essential upgrade |
| OPG and CBCT | Large purchase; may need room works and shielding |
| Intraoral scanners | Replace impressions; improve patient experience |
| Milling units and printers | Enable same-day restorations and in-house aligners or guides |
| Sterilisation | Autoclaves, washer-disinfectors, tracking |
| Compressors and suction | Essential plant, often overlooked until it fails |
| Lasers and microscopes | Specialist and endodontic work |
| Practice IT | Servers, workstations, imaging software, practice management |
How do lenders look at dental equipment?
A lender will usually want to understand three things:
- What it costs, all in. Equipment, delivery, installation, room works, software licences and training.
- What it does for the practice. Replacing worn gear keeps you trading; a scanner or CBCT that brings work in-house or attracts new patients adds revenue. Both are fundable, but new revenue strengthens the case.
- Whether repayments suit the practice. Based on collections and bank statements for a trading practice.
Past credit issues and ATO debt are considered case by case, so don’t let an older issue stop you asking.
Which structure suits dental equipment?
- Equipment finance ties the funding to the item, with a term that suits its expected life. business.gov.au’s guide to leasing or buying equipment explains the trade-offs between owning and leasing.
- Unsecured facilities for trading practices, typically $5,000 to $500,000 worked out from your turnover and recent bank statements, suit single items or small packages.
- Property-secured loans from $20,000 to $5,000,000, as first or second mortgages or caveats over residential or commercial property, suit a new surgery, a full refit or a large imaging package combined with works.
If you have a supplier quote, a quick enquiry is the fastest way to see which fits.
How do tax rules affect the timing?
Two ATO rules often shape when a practice buys:
- Instant asset write-off. The ATO says the $20,000 threshold is permanent from 1 July 2026 for small businesses with aggregated turnover under $10 million, applied per asset. Sensors, some scanners, sterilisation equipment and IT may fall under the threshold. Chairs and CBCT units usually don’t, and are depreciated instead.
- GST credits. The ATO says you can still claim credits for GST in purchases you use to make GST-free sales. Many dental services are GST-free, so a GST-registered practice can often claim the GST on equipment. Cosmetic services can be treated differently, so ask your accountant how your mix of services affects the claim.
Our instant asset write-off guide explains how clinics plan purchases around the end of financial year.
Don’t forget the room
Imaging and chairs often need changes to the room: plumbing, electrical, data, cabinetry and, for some imaging, shielding. Get the supplier and builder to quote together so nothing falls between the two. If the room works are substantial, fund them as part of a clinic fit-out.
An illustrative example
Illustrative only. A three-chair suburban practice refers all its crowns to a lab and has an ageing OPG. The principal wants to add an intraoral scanner and milling unit, and replace the OPG with a CBCT so implant planning can be done in-house. Room works are needed for the CBCT. With steady collections and a spare surgery, the practice could fund the scanner and mill through an unsecured facility and the CBCT and room works through a secured loan over the principal’s home, keeping cash free for marketing the new services.
Replacing chairs across a practice
Many practices replace chairs one surgery at a time as they age. That spreads the cost, but it can leave the practice with mismatched equipment and repeated disruption. Replacing several at once during a planned refurbishment may be more efficient. There’s no single right answer. Use the fit-out and equipment calculator to compare the funding need for a staged upgrade against doing it all at once.
Questions to ask the supplier before you sign
- What’s included: delivery, installation, software, training and first service?
- What room works are needed, and who is responsible for them?
- How long is the warranty, and what does ongoing service cost?
- How long will parts and software support be available?
- What’s the realistic lead time from order to installation?
The answers shape the true cost, and they tell a lender that the purchase has been thought through.
See what your practice could qualify for
You know exactly what the new equipment will mean for your patients. We can help with the rest. The enquiry takes about 60 seconds, with no credit check involved. Your details aren’t circulated among lenders, so there’s no barrage of calls. A person who knows dental practice finance will look at your situation and call you.
Please be accurate on the form (equipment cost, purpose, your state and any property available) so the first call gets you the right option.
Frequently asked questions
Can I finance a CBCT unit?
Yes. CBCT is usually one of the largest single purchases a dental practice makes. It's commonly funded through equipment finance, an unsecured facility sized on turnover, or as part of a secured loan. Include any room works and shielding in the amount.
Is it better to finance chairs one at a time or all together?
It depends on your plans. Replacing chairs as they age spreads the cost naturally. If you're refurbishing, funding them together with the room works can be simpler and may reduce disruption.
Can finance cover an intraoral scanner and milling unit for same-day restorations?
Yes. Lenders will often look favourably on equipment that brings work in-house or adds a new service, because it has a clear link to revenue.
Does used dental equipment qualify for finance?
Often. Used chairs and imaging can be funded, though lenders may want to know the age, condition and service history. Some items are harder to fund second-hand if support or parts are ending.
Will you check my credit when I enquire?
No. There's no credit check at the enquiry stage. It's only discussed if you decide to proceed.